
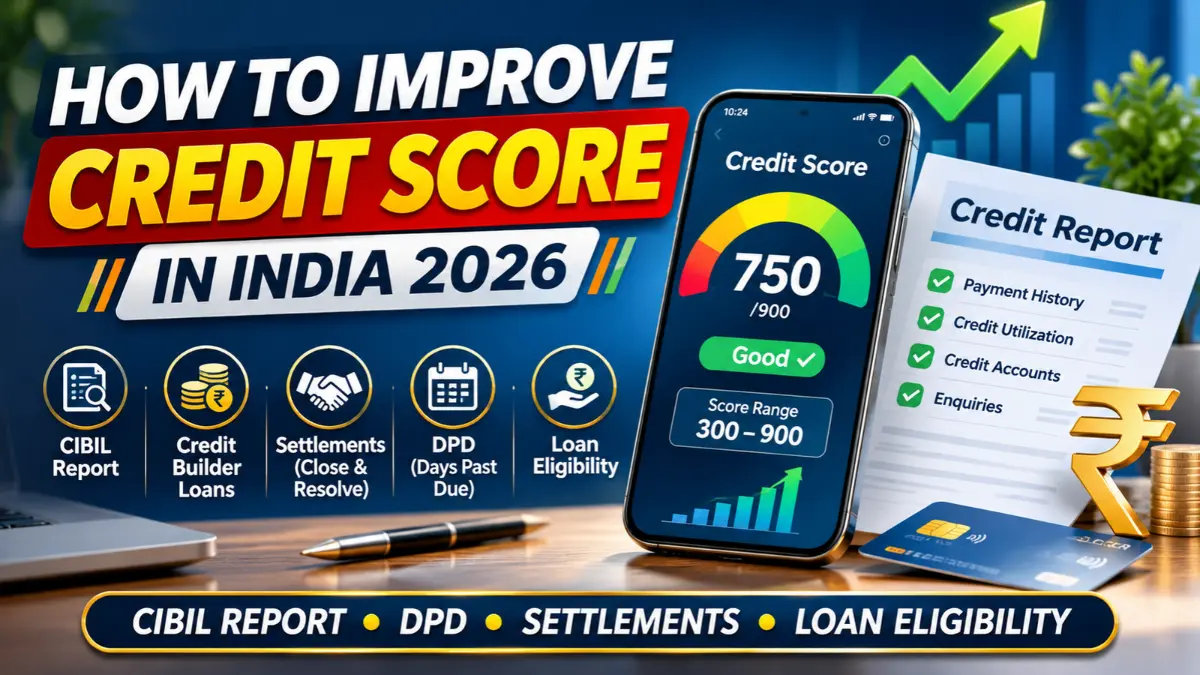
Improving your credit score in India is not about shortcuts or “credit repair hacks” — it is about building a clean, consistent and responsible credit history over time. A strong credit score, generally 750 or above, can help you get personal loans, home loans, car loans and credit cards at lower interest rates and with better approval chances.
Your credit report is maintained by four licensed Credit Information Companies (CICs) in India — TransUnion CIBIL, Equifax, Experian and CRIF High Mark. Each bureau may show a slightly different score because lenders report data to them at different times and use different scoring models.
What Is a Credit Score and Credit Report?
A credit score is a three-digit number, usually between 300 and 900, that reflects how responsibly you have handled credit in the past. A credit report is the detailed record behind that score — it shows your loans, credit cards, payment history, outstanding balances, credit enquiries and personal details.
Lenders use this report to decide whether to approve your loan, what interest rate to offer and how much credit limit to give. A higher score generally means lower risk for the lender, which translates to better terms for you.
Credit score ranges and what they mean
| Score range | What it means | Loan approval chances |
|---|---|---|
| 300–549 | Poor | Very low; most lenders will reject |
| 550–649 | Fair | Low; may get approval at high interest |
| 650–749 | Good | Moderate; decent approval chances |
| 750–799 | Very good | High; better interest rates |
| 800–900 | Excellent | Very high; best rates and terms |
A score of 750 or above is generally considered the “sweet spot” for most lenders in India. Below 700, approval chances drop significantly and interest rates go up.
How Many Credit Bureaus Are There in India?
There are four licensed Credit Information Companies (CICs) in India, regulated by the Reserve Bank of India (RBI):
- TransUnion CIBIL – The most widely used bureau, especially by banks and NBFCs.
- Equifax Credit Information Services – Popular for its detailed reports and analytics.
- Experian Credit Information Company of India – Known for its global presence and scoring models.
- CRIF High Mark Credit Information Services – Strong in microfinance and small-ticket lending data.
Each bureau may show a slightly different score because lenders report data to them at different times and use different scoring algorithms. Your CIBIL score might be 780 while your Experian score is 765 — this is normal and not an error.
Which bureau matters most?
For most retail loans (personal loan, home loan, car loan), CIBIL is the most commonly checked bureau by Indian lenders. However, many lenders now check multiple bureaus before approving a loan, so it’s wise to monitor all four reports periodically.
How to Check Your Credit Report for Free
You are entitled to one free credit report per year from each of the four bureaus, as per RBI guidelines. You can also check your score for free through various fintech apps and bank portals.
Steps to check your credit report
- Visit the official website of CIBIL, Equifax, Experian or CRIF High Mark.
- Register with your PAN, Aadhaar and mobile number.
- Verify your identity through OTP.
- Download your credit report and score.
- Review all sections carefully — personal details, loan accounts, credit cards, enquiries and payment history.
You can also check your score for free through apps like Paytm, PhonePe, CRED or your bank’s mobile app, though these usually show only one bureau’s score.
How to Increase Your Credit Score: 10 Proven Tips
Improving your credit score takes time and consistency, but these 10 tips are proven to work:
1. Pay Your EMIs and Credit Card Bills on Time
This is the single most important factor. Late payments are viewed very negatively by lenders and can drop your score significantly. Set up auto-debit or reminders to never miss a due date.
2. Keep Your Credit Utilisation Ratio Low
Try to use no more than 30% of your total credit limit across all cards. If your total limit is ₹1 lakh, try to keep outstanding below ₹30,000. High utilisation signals credit hunger and lowers your score.
3. Maintain a Healthy Credit Mix
Having a mix of secured loans (home loan, car loan) and unsecured loans (personal loan, credit card) is viewed positively. Too many unsecured loans can be a red flag.
4. Avoid Multiple Loan Applications in a Short Span
Each loan or credit card application triggers a “hard enquiry” on your report, which can temporarily lower your score. Apply for new credit only when genuinely needed.
5. Keep Old Credit Accounts Open
Older accounts with a clean payment history add to your credit age, which is a positive factor. Avoid closing old credit cards unnecessarily.
6. Monitor Co-Signed, Guaranteed and Joint Accounts
If you have co-signed a loan or guaranteed someone else’s loan, their missed payments will affect your score too. Monitor these accounts monthly.
7. Review Your Credit Report Regularly
Check your report at least once every 3–6 months to catch errors early. Incorrect overdue amounts, duplicate accounts or accounts that don’t belong to you should be disputed immediately.
8. Dispute Incorrect Information Promptly
If you find errors — wrong personal details, incorrect overdue amounts, duplicate accounts or unauthorised enquiries — raise a dispute with the bureau. CIBIL typically takes up to 30 days to resolve a dispute.
9. Avoid Taking Loans to Repay Loans
Taking a new loan just to repay an existing one (loan against loan) is a red flag and can lower your score further. It signals financial distress to lenders.
10. Use a Secured Credit Card if You Have No Credit History
If you’re new to credit, a secured credit card (backed by an FD) is a good way to start building history. Use it responsibly and pay bills on time to build a positive score.
Also Read: TVS Apache RTR 125 Unveiled at EICMA 2026: 14.7bhp, Mileage, Expected India Price, Full Specs
Credit Builder Loan: A Smart Way to Build Credit From Zero
A credit builder loan is a small, structured loan designed specifically to help people with no credit history or a low score build a positive credit profile. Unlike a normal loan where you get the money upfront, in a credit builder loan the amount is typically locked in a savings account or FD and released only after you complete all EMIs.
How it works
- You apply for a credit builder loan (usually ₹5,000–₹50,000).
- The lender opens a locked savings account or FD in your name with the loan amount.
- You pay fixed monthly EMIs over 6–24 months.
- Each on-time EMI is reported to credit bureaus (CIBIL, Experian, Equifax, CRIF).
- Once all EMIs are paid, the locked amount is released to you.
Benefits of credit builder loan
- Builds credit history from scratch.
- Low risk since the amount is secured.
- Reported to all major bureaus.
- Helps establish payment discipline.
- Can improve score by 50–100 points over 6–12 months if paid on time.
Risks of credit builder loan
- Missing even one EMI can hurt your score.
- Interest and processing fees may apply.
- Not a quick fix — takes 6–12 months to show results.
Credit builder loans are offered by some NBFCs and fintech apps in India. They report repayments to CIBIL, Experian, Equifax and CRIF High Mark, helping build a stronger credit profile over time.
FD-Backed Credit Card: Another Way to Build Credit
If you have no credit history or a low score, an FD-backed credit card (also called a secured credit card) is one of the best ways to start building credit. You deposit a fixed amount (usually ₹20,000–₹50,000) in an FD, and the bank issues a credit card with a limit equal to or close to that FD amount.
How it works
- You open an FD with the bank.
- The bank issues a credit card with a limit linked to the FD.
- You use the card for regular expenses.
- You pay the bill in full every month.
- Over 6–12 months, your credit history builds and your score improves.
This is a low-risk way to build credit because the bank has the FD as collateral. Once your score improves, you can apply for a regular (unsecured) credit card.
Loan Against Loan: Why It’s a Bad Idea
Taking a new loan just to repay an existing loan — often called “loan against loan” or “debt stacking” — is generally a bad idea and can hurt your credit score further.
Why it’s risky
- It signals financial distress to lenders.
- It increases your overall debt burden.
- It can lead to a debt trap if not managed carefully.
- It may result in multiple hard enquiries on your report.
- It can lower your credit score further.
Instead of taking a new loan to repay an old one, consider:
- Negotiating with your current lender for a restructuring or extension.
- Using savings or emergency funds.
- Selling unused assets.
- Seeking help from a financial counsellor.
Consumer Loan: What It Is and How It Affects Your Score
A consumer loan (also called a personal loan or consumer durable loan) is an unsecured loan taken for personal expenses like buying electronics, furniture, travel or medical emergencies. These loans are easy to get but can hurt your score if not managed well.
How consumer loans affect your score
- Positive impact: Timely EMI payments build a positive payment history.
- Negative impact: Multiple consumer loans in a short span signal credit hunger.
- High interest rates: Consumer loans often carry high interest rates (15–24%), making them expensive.
- Debt trap risk: Easy availability can lead to over-borrowing.
Use consumer loans sparingly and only for genuine needs. Avoid taking multiple small loans for lifestyle expenses.
Settlement, Write-Off and DPD: How They Affect Your Score
This is one of the most misunderstood areas of credit scoring. Many people think that “settling” a loan is a good thing, but it actually hurts your score.
What is a settlement?
A settlement means you paid less than the full outstanding amount, with the lender’s consent. For example, if you owed ₹1 lakh and settled for ₹70,000, the remaining ₹30,000 is written off by the lender. This is reported as “Settled” on your credit report.
Impact of settlement on credit score
- Negative impact: Settlement is viewed negatively by lenders because it shows you couldn’t repay the full amount.
- Score drop: Can drop your score by 50–150 points depending on the amount and history.
- Long-term effect: The “Settled” status stays on your report for up to 7 years.
- Future loan approval: Lenders may reject future loan applications or offer higher interest rates.
What is a write-off?
A write-off happens when you fail to make payments for more than 180 days. The lender then writes off the amount as a loss and reports it as “Written Off” on your credit report.
Impact of write-off on credit score
- Very negative impact: Write-off is worse than settlement.
- Score drop: Can drop your score by 100–200 points.
- Long-term effect: The “Written Off” status stays on your report for up to 7 years.
- Future loan approval: Very difficult to get approval for new credit.
What is DPD (Days Past Due)?
DPD (Days Past Due) shows how many days a payment on an account is late in a given month. Anything other than “000” or “STD” is considered negative by lenders.
| DPD status | Meaning | Impact on score |
|---|---|---|
| 000 / STD | Payment made on time | Positive |
| 30 | Payment 30 days late | Slight negative |
| 60 | Payment 60 days late | Moderate negative |
| 90 | Payment 90 days late | Significant negative |
| 120+ | Payment 120+ days late | Severe negative |
| XXX | Account written off or settled | Very negative |
Even a single late payment (30 days late) can lower your score for months. Multiple late payments have a compounding negative effect.
How to fix a settlement or write-off
- If the settlement was genuine, the status will remain on your report for up to 7 years.
- If the settlement was reported incorrectly (e.g., you paid in full but it shows “Settled”), raise a dispute with the bureau immediately.
- If the write-off was due to identity theft or fraud, file a police complaint and dispute it with the bureau.
- Over time, as you build new positive credit history, the impact of old settlements/write-offs reduces.
Hard Enquiry vs Soft Enquiry: What’s the Difference?
Every time you apply for a loan or credit card, the lender pulls your credit report. This is called a hard enquiry (or hard pull). In contrast, when you check your own score or a lender does a pre-approval check, it’s a soft enquiry (or soft pull).
Key differences
| Feature | Hard Enquiry | Soft Enquiry |
|---|---|---|
| Triggered by | Loan/credit card application | Self-check, pre-approval, employer check |
| Impact on score | Temporary drop (5–10 points) | No impact |
| Visible to lenders | Yes | No (only visible to you) |
| Duration on report | 2 years | Not reported |
| Multiple in short span | Red flag, lowers score | No issue |
How to minimise hard enquiries
- Apply for credit only when genuinely needed.
- Space out applications by at least 3–6 months.
- Use pre-qualification tools (soft pull) before applying.
- Avoid “shopping around” for loans within a short window.
- Check your report for unauthorised hard enquiries and dispute them.
Incorrect Details on Your Credit Report: How to Fix Them
Errors on your credit report are more common than you think. Common errors include:
- Wrong personal details (name, address, PAN, date of birth).
- Incorrect overdue amounts.
- Accounts that don’t belong to you (identity theft).
- Duplicate loan or credit card accounts.
- Wrong account status (showing “closed” when it’s active, or vice versa).
- Unauthorised hard enquiries.
- Wrong credit limit or outstanding balance.
- Incorrect DPD (Days Past Due) entries.
How to dispute errors
- Get your credit report from the bureau.
- Identify the error clearly.
- Go to the bureau’s dispute resolution page (e.g., CIBIL’s Consumer Dispute Resolution).
- Fill the dispute form with correct details.
- Attach supporting documents if needed.
- Submit and note the dispute ID.
- Wait for resolution (usually up to 30 days).
RBI’s 30-Day Resolution Rule and Compensation
RBI has mandated that credit institutions (banks/NBFCs) must respond to a dispute within 21 calendar days, and the Credit Information Company (CIC) must resolve the complaint within 30 calendar days from the date of filing. If the complaint is not resolved within 30 days, you are entitled to compensation of ₹100 per calendar day of delay, credited to your account within 5 working days of resolution.
This is a strong consumer protection measure that ensures errors are fixed quickly and lenders are held accountable.
How Much Credit Score Is Needed for Which Loan?
Different loans require different credit scores. Here’s a general guide:
| Loan type | Minimum score needed | Ideal score |
|---|---|---|
| Personal loan | 700+ | 750+ |
| Home loan | 700+ | 750+ |
| Car loan | 700+ | 750+ |
| Credit card | 700+ | 750+ |
| Business loan | 700+ | 750+ |
| Education loan | 650+ | 700+ |
| Gold loan | No score needed (secured by gold) | — |
| Loan against property | 700+ | 750+ |
| Credit builder loan | No score needed (designed for building credit) | — |
A score of 750 or above gives you the best chances of approval and the lowest interest rates. Below 700, you may still get approval but at higher interest rates or with a co-applicant/guarantor.
How Long Does It Take to Improve Your Credit Score?
Improving your credit score is not an overnight process. Here’s a realistic timeline:
| Action | Time to see improvement |
|---|---|
| Paying off overdue amounts | 1–2 months |
| Reducing credit utilisation | 1–2 months |
| Disputing and correcting errors | 30–60 days |
| Building credit history with secured card | 6–12 months |
| Closing old debts and maintaining clean history | 6–12 months |
| Major score improvement (100+ points) | 6–12 months |
Consistency is key. Even small, consistent improvements over 6–12 months can lead to a significant score increase.
Common Mistakes to Avoid
- Applying for multiple loans or credit cards in a short span.
- Using more than 30% of your credit limit.
- Closing old credit accounts unnecessarily.
- Ignoring errors on your credit report.
- Taking loans to repay loans.
- Missing EMI or credit card due dates.
- Co-signing loans for unreliable borrowers.
- Not monitoring your credit report regularly.
- Falling for “credit repair” scams that promise instant score improvement.
Market Impact
With digital lending growing rapidly in India, credit scores are becoming more important than ever. Fintech companies and NBFCs are using alternative data (like utility bill payments, rent payments) alongside traditional credit scores to assess borrowers.
Possible impacts include:
- More people becoming credit-aware.
- Easier access to credit for thin-file borrowers.
- Better risk assessment for lenders.
- More competitive interest rates for high-score borrowers.
- Growth in credit-monitoring services.
Also Read: Radhika Merchant’s “Ex-Boyfriend” Photos Viral: The Full Truth
Frequently Asked Questions (FAQs)
How can I increase my CIBIL score fast?
Pay overdue amounts immediately, reduce credit utilisation below 30%, dispute errors on your report, and avoid new loan applications for a few months.
How many credit bureaus are there in India?
There are four licensed credit bureaus in India — TransUnion CIBIL, Equifax, Experian and CRIF High Mark.
How long does it take to improve my credit score?
Minor improvements can be seen in 1–2 months, but major improvements (100+ points) usually take 6–12 months of consistent good behaviour.
What is a good credit score in India?
A score of 750 or above is considered very good, while 800+ is excellent. Below 700, approval chances drop significantly.
Can I get a loan with a low credit score?
Yes, but at higher interest rates or with a co-applicant/guarantor. Secured loans (gold loan, loan against property) may be easier to get with a low score.
What is an FD-backed credit card?
A secured credit card backed by a fixed deposit. You deposit an amount with the bank, and the card limit is linked to that FD. It’s a low-risk way to build credit.
What is a credit builder loan?
A small, structured loan designed to help people with no credit history or low score build credit. The amount is locked in a savings account/FD and released after all EMIs are paid.
How does settlement affect my credit score?
Settlement (paying less than full outstanding) is viewed negatively by lenders and can drop your score by 50–150 points. The “Settled” status stays on your report for up to 7 years.
How does write-off affect my credit score?
Write-off (no payment for 180+ days) is worse than settlement and can drop your score by 100–200 points. The “Written Off” status stays on your report for up to 7 years.
What is DPD and how does it affect my score?
DPD (Days Past Due) shows how many days a payment is late. Anything other than “000” or “STD” is negative. Even a single 30-day late payment can lower your score for months.
How do I dispute errors on my credit report?
Visit the bureau’s dispute resolution page, fill the dispute form with correct details, attach supporting documents, and submit. Resolution usually takes up to 30 days, with ₹100/day compensation if delayed beyond that.
Important Disclaimer
Credit score improvement tips and timelines mentioned above are based on general best practices and official guidance from CIBIL, RBI and other sources. Actual results may vary based on individual credit history and lender policies. Always verify with your bank or credit bureau before making financial decisions.

